 Chandra Wijayanto
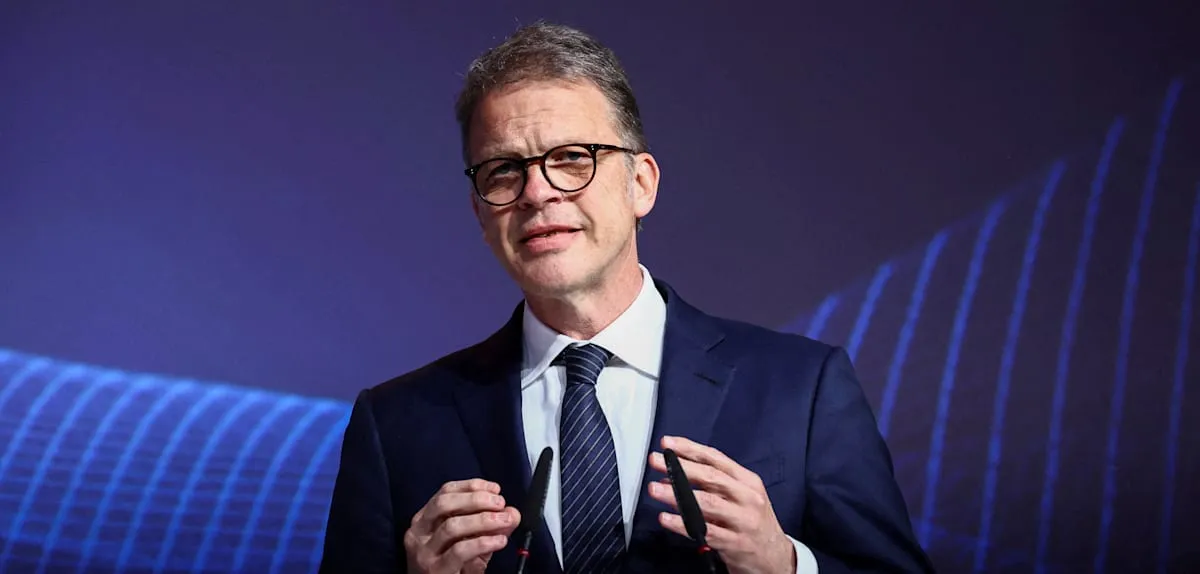
FRANKFURT – A wave of startling revelations is sweeping through the global banking sector as 13 million internal emails once again pull Deutsche Bank into a maelstrom of scandal linked to its relationship with convicted sex offender Jeffrey Epstein. Chief Executive Officer (CEO) Christian Sewing openly admitted this was a mistake that should never have happened, as the German financial giant faces potential new penalties looming in 2026.
The massive uncovering of millions of electronic correspondences, many originating from years-old transactions and communications, once again highlights the 'grey area' practices previously engaged in by the bank. Despite efforts at internal reform, the shadows of the past continue to haunt, demanding further accountability from the current management.
Sewing, who assumed leadership of Deutsche Bank after a tumultuous period, is at the forefront of the defense. He reaffirmed his commitment to ensuring full transparency and compliance with regulations. However, public and regulatory pressure is intensifying, especially after details of the Epstein transactions resurfaced.
In his statement, Sewing specifically highlighted a crucial email from 2017 that is now a focus of investigation. He explained the context and the steps taken since then to tighten compliance procedures and risk management across all bank operations. This statement aims to alleviate concerns and assert that the bank has learned from its fatal error.
The CEO's admission is not merely an expression of regret but also a strategic response to accusations threatening the bank's credibility. We have made fundamental changes. Our control structures are much stronger today than ever before, Sewing stated, emphasizing the internal restructuring efforts that have been ongoing for several years.
Beyond reputational concerns, Deutsche Bank now faces the threat of significant financial sanctions. Regulators, both in Germany and internationally, are evaluating the extent of the bank's negligence in conducting due diligence on high-risk clients like Epstein. Potential new fines could add to the financial burden of a bank still in recovery.
The Epstein case remains one of the darkest stains in modern banking history, where financial institutions are accused of facilitating illegal activities or at least being negligent about the origins of their clients' wealth. Deutsche Bank's role in Epstein's financial network has long been a subject of investigation, and these newly uncovered emails add a new dimension to the case.
The ongoing investigation focuses not only on individuals involved in the past but also on the bank's internal systems and processes. Law enforcement authorities aim to ensure that systems enabling suspicious transactions are no longer operational and that global banks have adequate safeguards against illicit activities.
This incident also reinforces the urgency for financial institutions to enhance their Anti-Money Laundering (AML) and 'Know Your Customer' (KYC) standards. Failure to comply with these standards not only damages reputation but can also lead to severe legal and financial consequences.
For additional information, The Leak of 15 Million Documents Reveals Deutsche Bank's 'Grey Area' Practices in 2026 previously underscored the pressure faced by the bank. That article provides further context on the scale of the data breach and its implications for Deutsche Bank's global operations.
Editorial Insight: The re-emergence of the Epstein scandal for Deutsche Bank is a crucial test of its integrity and the management's ability to truly sever ties with a problematic past. Sewing's admission, though belated, indicates immense pressure from regulators and the public. While the financial impact of new fines might be manageable, the long-term reputational damage poses a greater threat, demanding radical transparency and continuous reform to restore trust.